European Business Schools Librarian's Group
Finance Research Group Working Papers,
University of Aarhus, Aarhus School of Business, Department of Business Studies
Downloads from EBLSG
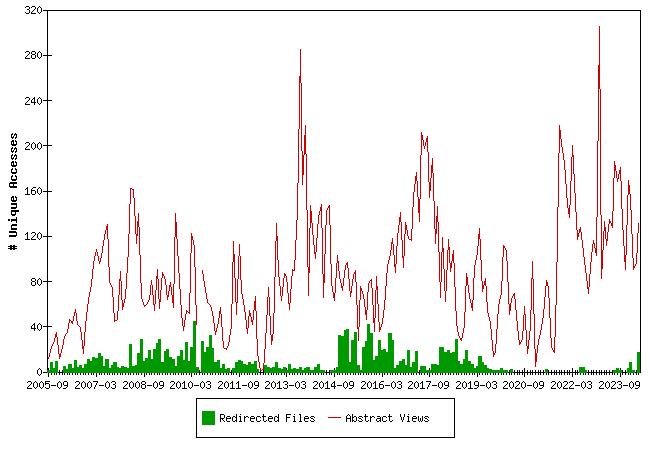
Fulltext files are files downloaded from the EBLSG server, Redirected files are files downloaded from a server maintained by the publisher of a working paper series.
The statistics for 2010-06, 2012-04 (half month), 2012-05 and 2012-06 have unfortunately been lost. We regret this.
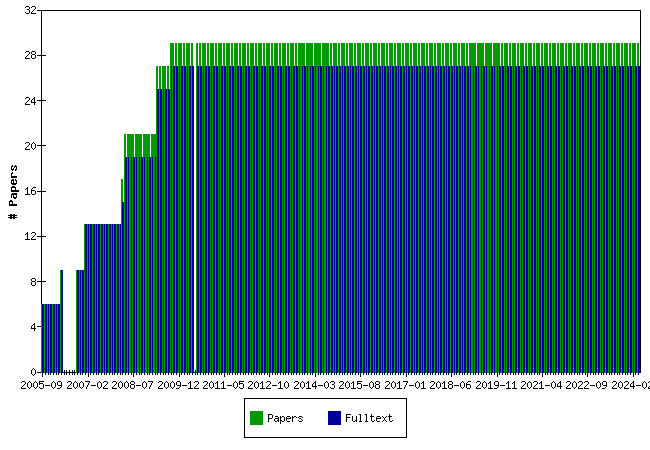
Papers at EBLSG
Top papers by Abstract Accesses last month (2026-10)
Top papers by Downloads last month (2026-10)
| Paper | Downloads |
|---|---|
| Realized Bond-Stock Correlation: Macroeconomic Announcement Effects Charlotte Christiansen, Angelo Ranaldo | 14 |
| Debt and Taxes: Evidence from bank-financed unlisted firms Jan Bartholdy, Cesário Mateus | 12 |
| Traffic Light Options Peter Løchte | 10 |
| Level-ARCH Short Rate Models with Regime Switching: Bivariate Modeling of US and European Short Rates. Charlotte Christiansen | 10 |
| Danish Mutual Fund Performance - Selectivity, Market Timing and Persistence. Michael Christensen | 10 |
| GSE Funding Advantages and Mortgagor Benefits: Answers from Asset Pricing Søren Willemann | 10 |
| Decomposing European bond and equity volatility Charlotte Christiansen | 8 |
| Do More Economists Hold Stocks? Charlotte Christiansen, Juanna Schröter Joensen, Jesper Rangvid | 8 |
| A Consistent Pricing Model for Index Options and Volatility Derivatives Rama Cont, Thomas Kokholm | 7 |
| Lapse Rate Modeling: A Rational Expectation Approach Domenico De Giovanni | 7 |
Top papers by Abstract Accesses last 3 months (2026-08 to 2026-10)
| Paper | Accesses |
|---|---|
| Improving the asset pricing ability of the Consumption-Capital Asset Pricing Model? Anne-Sofie Reng Rasmussen | 87 |
| Conducting event studies on a small stock exchange Jan Bartholdy, Dennis Olson, Paula Peare | 86 |
| The Fractional Ornstein-Uhlenbeck Process: Term Structure Theory and Application Espen P. Høg, Per H. Frederiksen | 84 |
| Traffic Light Options Peter Løchte | 77 |
| Time Charters with Purchase Options in Shipping: Valuation and Risk Management Peter Løchte Jørgensen, Domenico De Giovanni | 71 |
| Sato Processes in Default Modeling Thomas Kokholm, Elisa Nicolato | 70 |
| GSE Funding Advantages and Mortgagor Benefits: Answers from Asset Pricing Søren Willemann | 69 |
| Estimating US Monetary Policy Shocks Using a Factor-Augmented Vector Autoregression: An EM Algorithm Approach Lasse Bork | 68 |
| Investment Timing, Liquidity, and Agency Costs of Debt Stefan Hirth, Marliese Uhrig-Homburg | 68 |
| Paying for Market Quality Amber Anand, Carsten Tanggaard, Daniel G. Weaver | 67 |
Top papers by Downloads last 3 months (2026-08 to 2026-10)
| Paper | Downloads |
|---|---|
| Realized Bond-Stock Correlation: Macroeconomic Announcement Effects Charlotte Christiansen, Angelo Ranaldo | 19 |
| Debt and Taxes: Evidence from bank-financed unlisted firms Jan Bartholdy, Cesário Mateus | 18 |
| Traffic Light Options Peter Løchte | 16 |
| A Consistent Pricing Model for Index Options and Volatility Derivatives Rama Cont, Thomas Kokholm | 15 |
| Level-ARCH Short Rate Models with Regime Switching: Bivariate Modeling of US and European Short Rates. Charlotte Christiansen | 15 |
| Danish Mutual Fund Performance - Selectivity, Market Timing and Persistence. Michael Christensen | 15 |
| Decomposing European bond and equity volatility Charlotte Christiansen | 14 |
| GSE Funding Advantages and Mortgagor Benefits: Answers from Asset Pricing Søren Willemann | 13 |
| Sato Processes in Default Modeling Thomas Kokholm, Elisa Nicolato | 12 |
| Habit persistence: Explaining cross-sectional variation in returns and time-varying expected returns Stig Vinther Møller | 12 |
Top papers by Abstract Accesses all months (from 2005-09)
| Paper | Accesses |
|---|---|
| A Consistent Pricing Model for Index Options and Volatility Derivatives Rama Cont, Thomas Kokholm | 1566 |
| The Fractional Ornstein-Uhlenbeck Process: Term Structure Theory and Application Espen P. Høg, Per H. Frederiksen | 1555 |
| Traffic Light Options Peter Løchte | 1428 |
| Debt and Taxes: Evidence from bank-financed unlisted firms Jan Bartholdy, Cesário Mateus | 1413 |
| Conducting event studies on a small stock exchange Jan Bartholdy, Dennis Olson, Paula Peare | 1413 |
| Danish Mutual Fund Performance - Selectivity, Market Timing and Persistence. Michael Christensen | 1406 |
| Realized Bond-Stock Correlation: Macroeconomic Announcement Effects Charlotte Christiansen, Angelo Ranaldo | 1387 |
| On the Generalized Brownian Motion and its Applications in Finance Esben Høg, Per Frederiksen, Daniel Schiemert | 1244 |
| Paying for Market Quality Amber Anand, Carsten Tanggaard, Daniel G. Weaver | 1226 |
| Decomposing European bond and equity volatility Charlotte Christiansen | 1226 |
Top papers by Downloads all months (from 2005-09)
- University of Aarhus, Aarhus School of Business, Department of Business Studies
- Home page for this series
Questions (including download problems) about the papers in this series should be directed to Helle Vinbaek Stenholt ()
Report other problems with accessing this service to Sune Karlsson ().
This page generated on 2026-11-01 05:46:12.